Gross rental yield = annual rent ÷ property price × 100. A flat bought for £250,000 and let at £1,350 a month earns £16,200 a year, a gross yield of 6.48%. Net yield takes off running costs and empty periods first, and it is the figure that tells you whether the property actually pays.
The free rental yield calculator works out gross yield, net yield, monthly cash flow with or without a mortgage, and cash-on-cash return. The worked example below uses its default numbers so you can follow along.
What is rental yield?
Yield is the rent a property earns each year as a percentage of what it cost. It lets you compare properties of different prices on the same basis: a £150,000 flat and a £400,000 house can be ranked by how hard each one works for the money. It says nothing about capital growth, which is the other half of a property’s return.
How do you calculate gross rental yield?
- Multiply the monthly rent by 12 to get the annual rent.
- Divide by the purchase price or current value.
- Multiply by 100.
Example: £1,350 × 12 = £16,200. £16,200 ÷ £250,000 = 0.0648, so the gross yield is 6.48%.
Gross yield is quick and useful for comparing listings, which is why portals and agents quote it. But it ignores every cost, so two properties with the same gross yield can earn very different amounts.
How do you calculate net rental yield?
Net yield subtracts what it costs to run the property and allows for months when it is empty:
Net yield = (rent collected − annual running costs) ÷ (price + purchase costs) × 100
Continuing the example:
| Item | Amount |
|---|---|
| Annual rent at full occupancy | £16,200 |
| Rent collected, allowing 2 empty weeks | £15,577 |
| Letting and management at 10% | −£1,558 |
| Insurance, repairs, certificates, service charge | −£1,800 |
| Net operating income | £12,219 |
| Price plus £12,000 purchase costs | £262,000 |
| Net yield | 4.66% |
The gap between 6.48% and 4.66% is normal. Leasehold flats with high service charges can see a much bigger drop.
What costs should go into net yield?
- Letting or management fees, usually a percentage of rent, plus VAT where charged.
- Landlord insurance.
- Repairs and maintenance; many landlords allow 5–10% of rent.
- Service charge and ground rent on leasehold property.
- Safety certificates and checks required where you let, such as gas and electrical safety in the UK.
- Licensing fees, where a local scheme applies.
- Empty periods between tenancies.
- Purchase costs: stamp duty or transfer tax, legal fees, survey and any refurbishment.
Mortgage payments are left out of net yield on purpose, because they depend on how the purchase is financed, not on the property. They come into cash flow instead.
How does a mortgage change the picture?
With a 25% deposit, the example borrows £187,500. At 5.2% interest only, that is about £813 a month, or £9,750 a year. Net operating income of £12,219 minus £9,750 leaves £2,469 a year of cash flow, about £206 a month.
A repayment mortgage costs more each month because part of every payment reduces the loan. Cash flow is lower, but you build equity. Switch between the two in the calculator to see the difference.
What is cash-on-cash return?
Cash-on-cash return compares the cash flow with the cash you actually put in: the deposit plus purchase costs.
Cash-on-cash = annual cash flow ÷ (deposit + purchase costs) × 100
In the example: £2,469 ÷ (£62,500 + £12,000) = 3.31%. It is a useful check on whether leverage is helping. If the cash-on-cash return is below what the same money would earn elsewhere, the case rests on capital growth.
What is a good rental yield?
There is no single number. Yields are usually higher where prices are lower, and lower in expensive cities where buyers expect more capital growth. A higher gross yield often comes with more management, more wear and more risk of voids. Compare properties on net yield and cash flow, and against local rents you can evidence, not the asking rent in an advert.
What does rental yield leave out?
Tax, for one. Income tax on rental profit, and rules such as the UK restriction on mortgage interest relief for individual landlords, which gives a basic-rate tax credit rather than a deduction, can change the real return a great deal. It also leaves out capital growth, refinancing and the cost of your own time. Use yield to compare and shortlist, then speak to a broker or tax adviser before buying.
How do you increase a rental property’s yield?
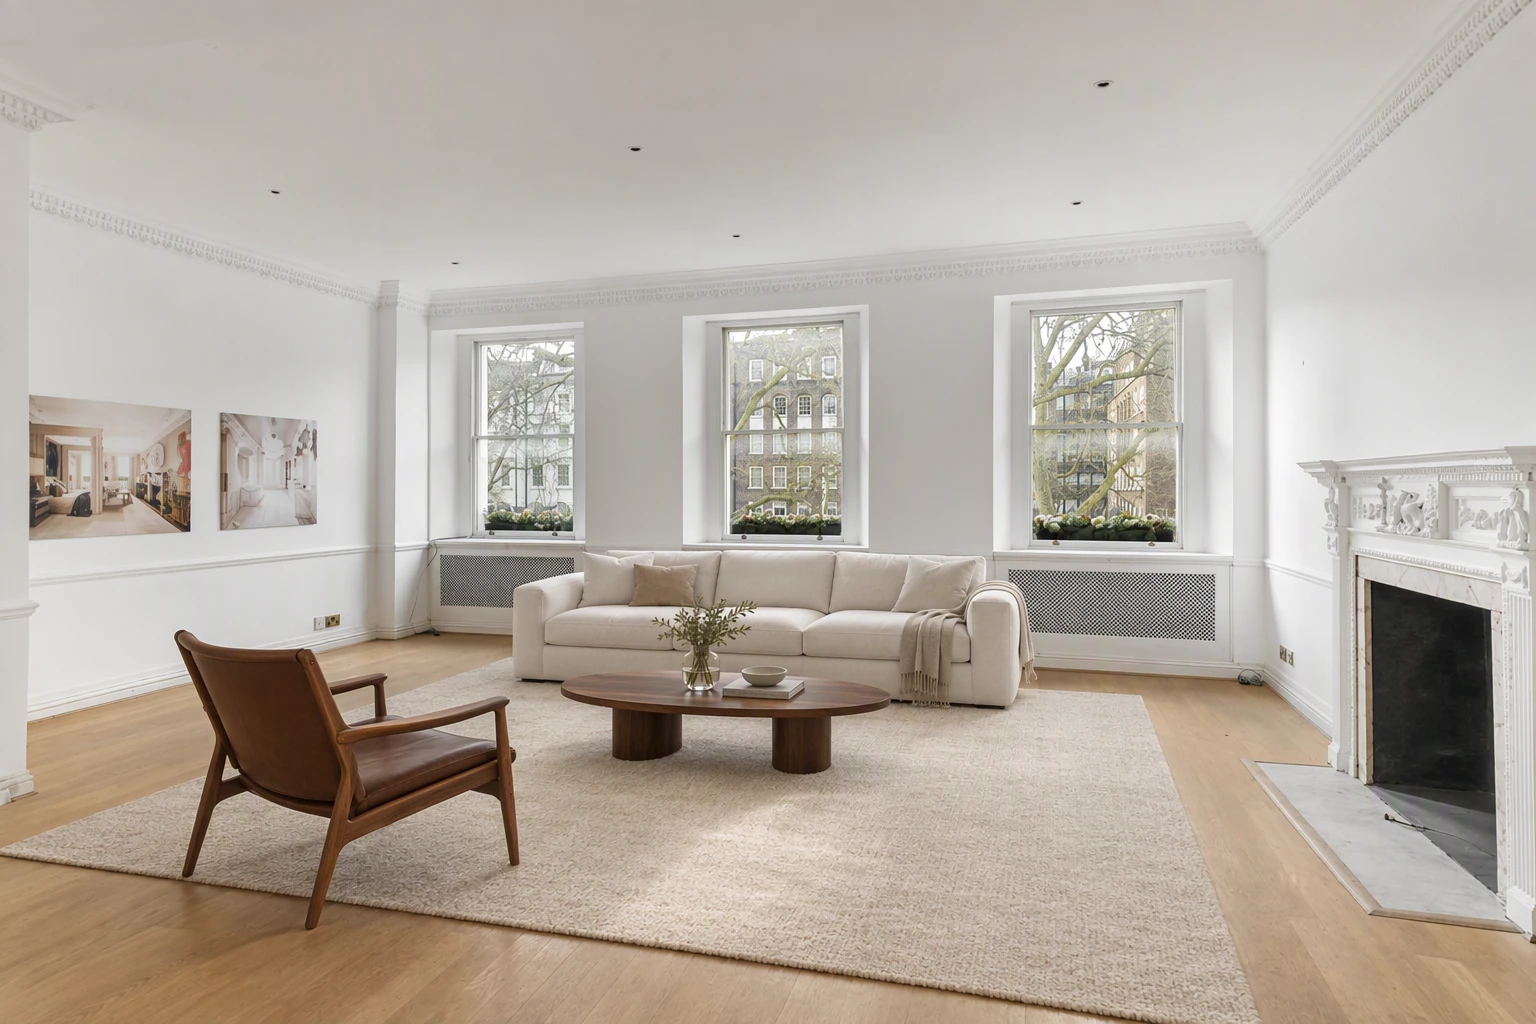
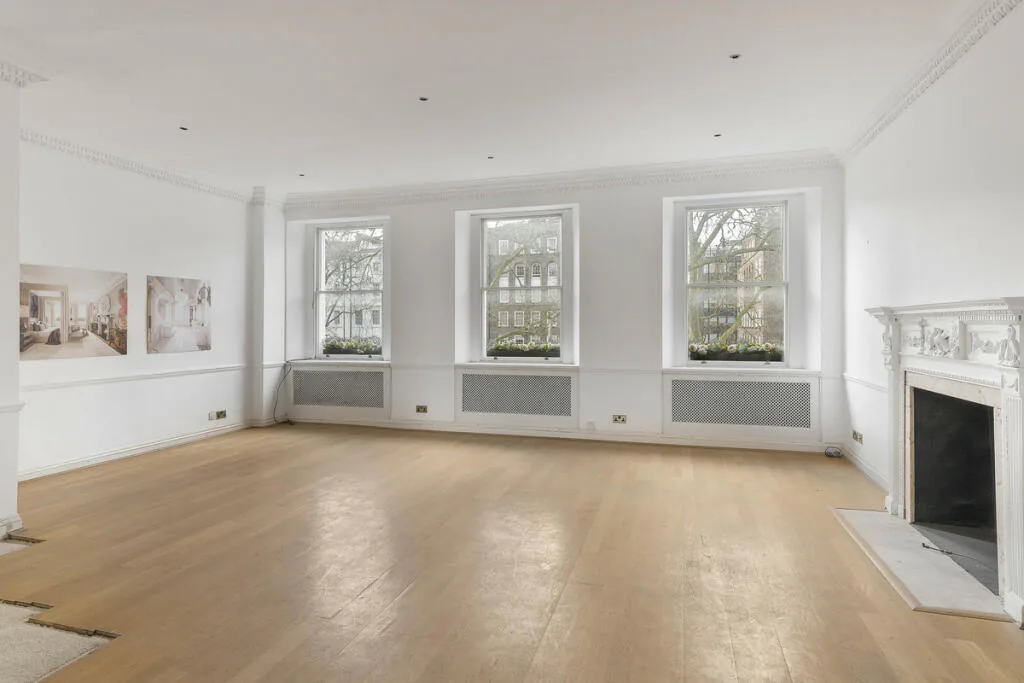
Either raise the rent, cut the costs or shorten the empty weeks. Presentation helps with the third. A listing with bright photos, a furnished look and a tour tenants can explore before booking a viewing gets more enquiries in the first days on the market. Splatr can furnish an empty flat’s photos, make a vertical video for social and share a 360° tour, which is how property managers use Virtual Studio. For part-month rent at the start of a tenancy, use the prorated rent calculator.
Put the guide into practice.
Turn your own photos into edited images and videos in minutes.
7-day free trial.